

Heading into yesterday's rate hike, recent evidence suggested the longer end of the bond market would appreciate a hike. There was no telling exactly how this would impact rates on Fed day itself--only that it was probably the lesser of two evils in the coming weeks. It was highly reassuring to see essentially no reaction to the rate hike in the first 30 minutes. But the press conference introduced additional selling pressure (obviously). Now this morning, bonds have gone a long way toward fulfilling the paradoxical prophecy. Even though a good amount of credit must be given to lower oil prices, there is still excess positive momentum in bonds that can't be explained by oil.
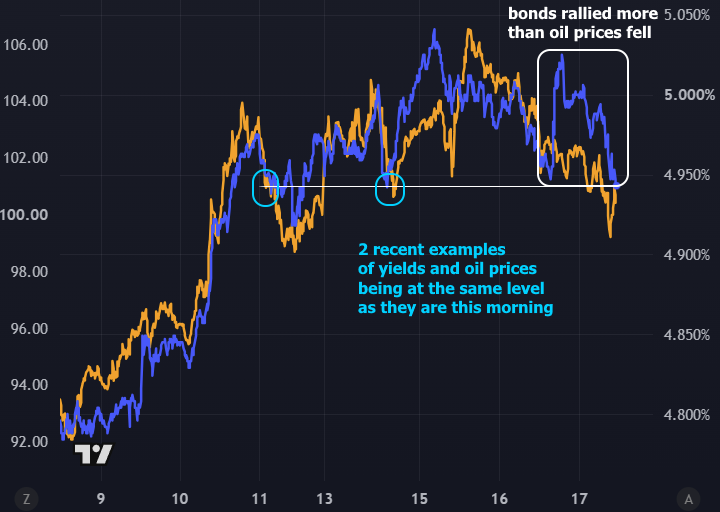
The following chart shows bond yields dropping much faster than oil prices this morning in order to return to a more correlated trend. This is a demonstration of excess strength in bonds because they've generally been doing a bit worse than a 1:1 oil price correlation would suggest. Most simply, there are several times in the past week where both yields and oil prices were at the same levels they are this morning. In other words, there's no longer any lasting evidence of yesterday's Fed press conference sell-off.